LPPSA Calculator: How Much Can You Borrow to Build Your House?
Don't fall in love with a house that is beyond your eligibility. Check first — in under a minute — and we show you the amount, the monthly instalment, the tenure, and which rule is limiting you, so you know exactly what can change.
- LPPSA rate
- 4.00%
- fixed
- LPPSA financing limit
- RM1,000,000
- Bank rate assumed
- 4.30%
- floating
Work out your home loan eligibility: LPPSA and bank
Pension-scheme staff may repay over up to 420 months or to age 90, whichever comes first; EPF-scheme staff repay until the end of service (LPPSA guideline 2026).
Instalment capped at 60% of net income for a first facility, 50% for a second.
Assumptions used
- Fixed profit rate of 4.00% per year on a reducing balance, on financing up to RM750,000; 4.50% on any balance above that.
- Net income of RM4,300: basic pay plus fixed allowances, minus mandatory deductions (EPF, SOCSO, tax), as LPPSA defines it.
- Instalment capped at 60% of net income (first facility).
- Total debt servicing not exceeding 80% of net income.
- Tenure of 25 years — EPF scheme: age 35 to the end of service at 60, maximum 35 years.
- Capped by LPPSA's maximum-eligibility table for your net income band: RM510,000.
- Maximum financing limit of RM1,000,000, as announced by LPPSA in 2026 (applications expected to open in Q4 2026).
Rates effective 2026-09-23 (version 2026.09d). The final decision rests entirely with LPPSA, not with RumahHQ.
Estimated financing amount
RM318,000
Rounded DOWN to the nearest RM1,000. We deliberately do not round up.
- Monthly instalment
- RM1,680
- Tenure
- 25 years
Your binding constraint
Instalment cap on net income
Your eligibility is capped by the share of net income that can go to an instalment. Raising fixed income or clearing a commitment lifts this figure.
Why, and what you can doThe link holds the figures you entered. It stays on your device until you share it.
16 min read · Checked
Share on WhatsAppShort answer
- LPPSA: 4.00% fixed, financing limit RM1,000,000, first-financing instalment up to 60% of net income.
- Bank: DSR 60% when net income is below RM5,000, 70% from that amount; the loan must be settled before age 70.
- This is an estimate, not an approval: LPPSA or the bank decides. Figures are rounded down to the nearest RM1,000.
- Enter every commitment, including PTPTN and your credit card minimum payment; the bank sees them all in CCRIS.
- If you fall short of your target: clear one small commitment, apply jointly with your spouse, or extend the tenure if your age allows.
The rules we apply
Every figure below is effective 2026-09-23. If one of them changes, this tool changes the same day.
LPPSA — public sector
- Profit rate
- 4.00% fixed
- Instalment cap — first facility
- 60% of net income
- Instalment cap — second facility
- 50% of net income
- Total debt servicing ceiling
- 80% of net income
- Minimum net salary retained
- 20%
- Maximum tenure
- 35 years, to retirement age
- Financing limit
- RM1,000,000
The RM1,000,000 limit follows LPPSA's 2026 announcement (applications expected to open in Q4 2026): 4.00% up to RM750,000, and 4.50% on the balance above it. This tool calculates both portions.
Bank loan — private sector
- Rate assumed
- 4.30% floating
- Net income — salaried
- 82% of gross
- Net income — self-employed
- 90% of gross
- DSR — net below RM5,000
- 60%
- DSR — net RM5,000 and above
- 70%
- Margin of finance
- 90% / 80%
- Maximum age at maturity
- 70 years
Bank rates are floating and campaign-dependent, which makes them the fastest-ageing thing on this site. They are shown with a date, not as a promise.
The figures you enter decide the answer
This calculator is only as accurate as the figures you give it. Most answers that come out too high come from two mistakes: gross income entered as if it were net, and small commitments forgotten. This is how LPPSA and the banks count both.
LPPSA mode: enter income the way LPPSA counts it
The calculator works the way LPPSA does, on net income: basic salary, plus the fixed allowances it counts, minus the mandatory deductions on your payslip. To that it applies the 60% instalment cap, the 80% total debt ceiling and LPPSA's maximum eligibility table (Lampiran 1). So, for an accurate answer:
- Basic salary box: your full basic salary, as on your payslip.
- Mandatory deductions box: EPF (if any), SOCSO, PCB tax, court orders and government housing loans. Do not also take them off the basic salary, or they are counted twice.
- Allowances box: only the fixed allowances on LPPSA's list.
- Commitments box: other debt deductions on your payslip (cooperative loans, personal financing by salary deduction) and bank instalments paid outside your payslip. LPPSA does not deduct zakat, ASB, Tabung Haji or SSPN; entering them only makes the figure more cautious.
After that, LPPSA approves the lowest of the contract price, the JPPH valuation, the amount applied for and your eligibility. The full list of allowances, deductions and the table are on the LPPSA page.
Example: basic salary RM4,000 with RM300 of mandatory deductions
- Mandatory deductions box left empty
- RM428,000
- RM300 of mandatory deductions entered
- RM394,000
A difference of RM34,000. Fixed allowances RM600, a RM500 cooperative deduction as a commitment, age 35, retiring at 60, first facility. Illustrative figures only, computed with the same functions as the calculator above.
Bank mode: the commitments a bank sees
Bank Negara requires banks to assess affordability on income after tax and EPF, and to consider all debt obligations. In Malaysia, DSR counts loans from banks and from non-banks too. Put all of these in the commitments box:
- Car loans, personal loans and existing housing loans.
- PTPTN. PTPTN reports to CCRIS, so the bank sees the loan and its repayment record.
- Credit cards. Use the monthly minimum payment. On one published card, that is 5% of the outstanding balance plus all card instalment plans (balance transfers, instalment plans), or RM50, whichever is higher. Banks differ in how they count cards.
- Cooperative debts and financing repaid by salary deduction.
- Joint loans. CCRIS shows facilities you hold as a joint borrower. Ask the bank what share it counts against you.
- Guarantees. A guarantee is a contract that binds you to pay if the borrower fails to. Once the guarantee is called, the debt appears in your CCRIS as “Outstanding from Call of Guarantee”.
Besides DSR, banks also check net disposable income (NDI): what is left of net income after all instalments. Bank Negara states that minimum NDI thresholds differ between banks and may be set by income, risk profile, location and marital status. That is why two banks can give the same person different answers.
Example: one credit card with a RM6,000 balance
- No card balance
- RM499,000
- With a RM300 monthly card minimum
- RM434,000
Gross income RM6,000, salaried, age 35, car loan RM650 a month, property value RM900,000. Clearing that card balance before applying adds RM65,000 to this figure. Illustrative figures only, computed with the same functions as the calculator above.
A checklist before you apply
CCRIS shows 12 months, so start early. Each step below changes the figure the bank sees, not only the figure in the calculator.
- Pull your CCRIS report and your CTOS Basic Report. Make sure you recognise every facility in them.
- Clear any arrears first. A regularised month shows from the following month.
- Bring down credit card balances and card instalment plans; plan instalments count in full in the minimum payment.
- Take no new loan or instalment plan before applying. Each one adds a commitment, and a pending application shows in CCRIS.
- Have your salary paid into the same bank account every month; banks ask for statements showing it.
- If you are self-employed, file your taxes and keep a separate business account statement.
- Check whether you are a guarantor on anyone's loan.
- Work out your age at the end of the tenure. If the tenure is short, discuss a joint application with your spouse.
- Enter the corrected figures in the calculator above again, and compare the routes on LPPSA or a bank.
If your eligibility falls short
This happens to most applicants on the first pass, and it is almost always fixable. Five things that genuinely move the number, in order of effect:
- Clear one small commitment. Every RM100 of monthly instalment removed adds roughly RM20,000 of eligibility over 30 years.
- Apply jointly with your spouse. Two incomes are assessed together, and this is usually the largest single jump.
- Extend the tenure if your age allows it. A lower instalment supports a higher principal.
- Choose a smaller design or the Silver package. Dropping 200 sq ft is enough in many cases.
- Use EPF Akaun Sejahtera (formerly Account 2) to cover the gap, not to fund the whole build.
We can help you check all of this at no charge, including the document list. Contact us.
Free guide, in Malay
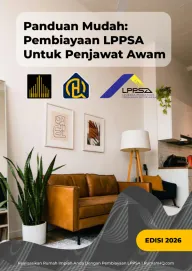
Panduan Mudah: LPPSA Financing for Civil Servants
Our team's 36-page guide: the seven types of LPPSA financing, who qualifies, the documents, takaful cover and legal fees, in plain Malay.
Download the guide (PDF, 5.3 MB)Written in November 2025, the book gives the old RM750,000 limit. LPPSA has since announced RM1,000,000.
We are a registered panel contractor

Golden Sharp Innovation (IP0580950-X) is a registered panel contractor with the institutions above. Panel status means our credentials as a contractor have been assessed, and our progress-claim documents follow the format these institutions expect — it is not a guarantee that your financing will be approved, and not an endorsement of our services by them. Approval and terms are determined entirely by LPPSA or the bank concerned. Logos and trademarks are the property of their respective owners.
For the detail-minded
Further reference
The rules and details behind the guide above. Open only what applies to you.
The income a bank accepts, and the proof
How the calculator estimates net income, and the documents banks ask for from salaried, commission, business and rental earners.
The calculator estimates net income as 82% of gross if you are salaried, and 90% if you are self-employed. If your payslip shows a net salary after EPF, SOCSO and tax that is very different, adjust the gross figure so the estimate matches your payslip.
- Fixed salary: payslips and bank statements showing the salary credited (one bank asks for the latest three months of both), an EPF statement, Form BE and the tax payment receipt.
- Commission or variable pay: one bank's published checklist (2017) asks for three to six months of payslips or commission slips, with Form BE or EA. Enter an average over several months, not your best month.
- Self-employed: business registration, Form B with the tax receipt, and six to nine months of bank statements. The full list is on the bank loan page.
- Rental: a stamped tenancy agreement.
Age, tenure and joint applications
The bank's tenure and age limits, a worked example of what age does to eligibility, and what a bank checks in a joint application.
The calculator uses a maximum bank tenure of 35 years, and the loan must be settled before age 70. The published home-construction and home-loan products we checked use the same limits. A shorter tenure means the same instalment finances a smaller amount.
Example: the same person at different ages
- Age 35, tenure 35 years
- RM499,000
- Age 48, tenure 22 years
- RM392,000
Income and commitments as in the card example above, with no card balance. The instalment is almost the same; only the number of years to pay it changes.
Joint applications. The calculator works out one applicant. In a joint application the bank checks both applicants' CCRIS and commitments, so a partner who already carries a lot of debt may not add much. Some products limit joint applicants to immediate family members. LPPSA's joint financing rules are on the LPPSA page.
Your credit record: check it before the bank does
How to get your free CCRIS and CTOS reports, correct mistakes, and what an AKPK programme shows.
A bank reads your credit report on every application. You can read the same report, free, and correct anything wrong well ahead.
CCRIS — Bank Negara Malaysia
Free, with no limit on how often. Get it through eCCRIS (register online with MyKad and internet banking; an RM1 verification transfer is refunded within two working days) or at a CCRIS kiosk in an AKPK office.
The report shows your active facilities, the number of instalments in arrears for each of the last 12 months (0 means none), accounts under “Special Attention”, and applications pending or approved in the last 12 months. Applications that were not approved are not shown. CCRIS is not a blacklist and gives no score.
CTOS and the credit reporting agencies
CTOS, Credit Bureau Malaysia and Experian are agencies under the Credit Reporting Agencies Act 2010. With your consent they can read CCRIS, and they may hold other information such as court actions. CTOS gives a free Basic Report twice a year (without CCRIS or a score) showing court actions, bankruptcy, directorships and trade referee listings. The CTOS Score is a three-digit number; the full report with the score is paid.
An agency may not show a default record more than two years after the date of final settlement. If a bank does not approve an application based on an agency report, you have the right to know which agency, and to see that report.
If something is wrong
- A wrong loan record: contact the complaints unit of the bank that reported it. Bank Negara does not change records; only the bank can. A response usually comes within 14 working days.
- Wrong personal details (name, identity card number): request a verification through eCCRIS.
- A loan you are disputing, for example over interest charges: the record stays, but Bank Negara can tag your report as “Special Name” while the dispute is decided.
- An error in a CTOS report: use the CTOS dispute process. Complaints against an agency can go to the Registrar of Credit Reporting Agencies at the Ministry of Finance.
- A debt you have just settled is updated by the bank by the 10th of the following month, but the arrears history stays until it drops out of the 12-month window.
If you are on an AKPK programme
Facilities under AKPK's Debt Management Programme (DMP) are reported in CCRIS with the status “Loan under Repayment Assistance Programme by AKPK”, so every bank that checks will see it. Each bank makes its own decision.
DMP instalments are paid to AKPK by the 5th of each month. AKPK terminates the programme after three consecutive months unpaid, and participants may withdraw after at least a year. Once an account is settled, submit the bank's release letter through the AKPK portal.